
Best Credit Cards for Beginners to Build Credit
If you’re starting your credit journey, the right first credit card can help you build a strong credit score 
 What is a credit score and How a good score can help you save money?, qualify for better financial products, and avoid costly mistakes. The best beginner credit cards in 2026 prioritize approval accessibility, low fees, and credit-building features over rewards. After reviewing beginner-friendly cards based on approval difficulty, fees, credit reporting policies, and upgrade options, we found these to be the best credit cards for building credit. The first two picks are unsecured, so there is no deposit. The last three are secured, which means a refundable deposit makes approval easier if you have no credit or poor credit.
1. Chase Freedom Rise
The Chase Freedom Rise is built for people who are new to credit and want an unsecured card with no security deposit. It earns a flat 1.5% cash back on every purchase, and Chase automatically reviews your account each year for an upgrade to the Chase Freedom Unlimited.

Chase Freedom Rise® Cash Back Rewards
Earn unlimited 1.5% cash back on all purchases while building credit. Rewards do not expire as long as your account stays open, and there is no minimum to redeem for cash back. Redeem for a statement credit, a deposit into an eligible Chase account, gift cards, travel, or Amazon checkout.
| Category | Reward Rate | CAP |
|---|---|---|
| Lyft Rides |
2%
Limited time offer
|
Through 9/30/2027; terms apply |
| All Purchases |
1.5%
Unlimited rewards
|
No limit |
Pros
- No annual fee and no security deposit
- Flat 1.5% cash back on every purchase
- Automatic yearly upgrade review to Chase Freedom Unlimited®
- Credit line increase review in as soon as 6 months
- Built-in purchase, warranty, and trip protections
Cons
- A Chase account with $250+ improves approval odds for first-time cardholders
- 3% foreign transaction fee
- 5% balance transfer fee (minimum $5)
- No bonus categories beyond a limited-time Lyft offer
- High APR if you carry a balance
The yearly fee charged to keep the card active.
A recurring monthly charge for this card.
Fee charged when transferring balances from another card.
Additional fee for purchases processed in foreign currencies.
Fee charged when withdrawing cash from your credit line.
Penalty fee if your payment is made after the due date.
Standard APR applied to regular purchases.
APR applied to balance transfers.
APR charged on cash advances, usually higher than regular APR.
Higher APR that can apply after late or missed payments.
Promotional APR available for an introductory period.
How long the introductory APR remains in effect.
Requirements
Additional Information
The Chase Freedom Rise® card is designed for people who are new to credit and want simple cash back while building a credit history. It has no annual fee and no security deposit. If you have never had a credit card, having at least $250 in a Chase checking or savings account can improve your approval chances, though it is not required and does not guarantee approval. Chase automatically reviews your account each year for an upgrade to Chase Freedom Unlimited®, and you can be considered for a credit line increase in as soon as 6 months. Chase may ask for additional verification after you apply, such as a U.S.-issued driver’s license and Social Security card.
Why we picked it: We selected this card because it is an unsecured starter card with no annual fee and a clear upgrade path. If you have never had a credit card, keeping at least $250 in a Chase checking or savings account can improve your approval chances.
2. Capital One Platinum Credit Card
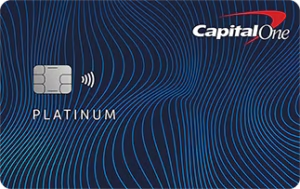
The Capital One Platinum Credit Card is an unsecured option for people with fair or limited credit who don’t want to tie up money in a security deposit. It has no annual fee and no foreign transaction fee, and Capital One may automatically consider you for a higher credit line in as little as six months. It doesn’t earn rewards, and its 28.99% variable APR is high, so pay your balance in full each month.
Last updated October 1, 2026
Credit Building Program
This card is designed to help you build or rebuild credit through responsible use and on-time payments. Capital One reports your account activity to all three major credit bureaus. After as little as 6 months you can be automatically considered for a higher credit line with no additional deposit, and you may work toward earning your refundable deposit back.
| Benefit | Value | Details |
|---|---|---|
| Security Deposit | $49, $99 or $200 | Refundable deposit based on your profile. Any of the three gets you a $200 starting credit line. |
| Credit Line Review | 6 months | Automatic consideration for a higher credit line in as little as 6 months, with no additional deposit needed. |
| Deposit Refund | Refundable | Use your card responsibly and pay on time to work toward earning your deposit back as a statement credit. |
| Fraud Protection | $0 liability | Zero liability protection against unauthorized charges, plus Mastercard ID Theft Protection. |
| Credit Monitoring | Free CreditWise | Monitor your credit score for free with CreditWise from Capital One. |
Pros
- Deposit as low as $49 for a $200 credit line
- Automatic credit line review in as little as 6 months
- No annual fee, no foreign transaction fee, and no penalty APR
- Check if you pre-qualify without a hard credit check
- Reports to all three major credit bureaus
Cons
- Security deposit required
- No rewards program
- Low $200 starting limit unless you deposit more
- High 28.99% variable APR
The yearly fee charged to keep the card active.
A recurring monthly charge for this card.
Fee charged when transferring balances from another card.
Additional fee for purchases processed in foreign currencies.
Fee charged when withdrawing cash from your credit line.
Penalty fee if your payment is made after the due date.
Standard APR applied to regular purchases.
APR applied to balance transfers.
APR charged on cash advances, usually higher than regular APR.
Higher APR that can apply after late or missed payments.
Promotional APR available for an introductory period.
How long the introductory APR remains in effect.
Requirements
Additional Information
The Capital One Platinum Secured Credit Card is built for people with limited or poor credit who want a low-cost way to start or rebuild a credit history. Depending on your application, your refundable security deposit is $49, $99, or $200, and your credit line starts at $200 in every case. That makes it one of the few secured cards where the credit line can be larger than the deposit. You can pick a higher line, up to $1,000, by depositing more, and you can see if you pre-qualify without a hard credit check. There is no annual fee, no foreign transaction fee, and no penalty APR, and Capital One automatically considers you for a higher line in as little as 6 months. The trade-offs are no rewards and a high 28.99% variable APR, so pay your balance in full each month.
Why we picked it: We chose this card because it pairs no deposit with no annual fee and a quick credit line review. If your credit is poor or you have no history at all, a secured card like the Capital One Platinum Secured below may give you better approval odds.
3. Discover It Secured
The Discover it Secured Credit Card is one of the few secured cards that earns cash back. You earn 2% at gas stations and restaurants on up to $1,000 in combined purchases each quarter and 1% on everything else, with a refundable deposit starting at $200.
Last updated October 1, 2026
Discover Cashback Bonus®
Earn 2% cash back at gas stations and restaurants on up to $1,000 in combined purchases each quarter, and 1% on everything else. Discover also matches all the cash back you earn during your first year. Rewards never expire while your account is open and can be redeemed as a statement credit, an electronic deposit, at select merchants, or for gift cards.
| Category | Reward Rate | CAP |
|---|---|---|
| Gas Stations |
2%
Up to $1,000 combined
|
Shared $1,000 quarterly cap with restaurants |
| Restaurants |
2%
Up to $1,000 combined
|
Shared $1,000 quarterly cap with gas stations |
| All Other Purchases |
1%
Default rewards
|
Unlimited |
Pros
- Cash back rewards, which are rare on secured cards
- Dollar-for-dollar Cashback Match after your first year
- No annual fee and no foreign transaction fee
- No late fee on your first late payment and no penalty APR
- Automatic reviews to move to an unsecured card
Cons
- $200 minimum refundable deposit
- High 26.49% variable APR
- Discover is not accepted everywhere outside the U.S.
- Deposit must be funded from a bank account
The yearly fee charged to keep the card active.
A recurring monthly charge for this card.
Fee charged when transferring balances from another card.
Additional fee for purchases processed in foreign currencies.
Fee charged when withdrawing cash from your credit line.
Penalty fee if your payment is made after the due date.
Standard APR applied to regular purchases.
APR applied to balance transfers.
APR charged on cash advances, usually higher than regular APR.
Higher APR that can apply after late or missed payments.
Promotional APR available for an introductory period.
How long the introductory APR remains in effect.
Requirements
Additional Information
The Discover it® Secured Credit Card is one of the few secured cards that earns cash back and charges no annual fee. Your credit line equals your refundable security deposit, which can range from $200 to $2,500, and you provide bank account information when you submit it. Discover reports to the three major credit bureaus and starts automatic reviews at around 7 months to see if you can move to an unsecured line of credit and get your deposit back. Discover does not charge a late fee the first time you pay late and does not raise your APR for a late payment. Discover is accepted at most U.S. merchants but may not be accepted in all countries outside the U.S.
Why we picked it: We chose this card because Discover matches all the cash back you earn in your first year, and it begins automatic reviews at around seven months to see if you can move to an unsecured card and get your deposit back.
4. Capital One Platinum Secured
The Capital One Platinum Secured Credit Card lets you start with a $200 credit line for a refundable deposit of $49, $99, or $200, depending on your profile. It has no annual fee and no foreign transaction fee, but it doesn’t earn rewards.
Last updated October 8, 2026
Credit Building Program
This card does not earn rewards. It is built to help you establish or improve credit with responsible use, without a security deposit. After as little as 6 months of on-time payments, Capital One may automatically consider you for a higher credit line.
| Benefit | Value | Details |
|---|---|---|
| Security Deposit | None | Unsecured card, so you do not tie up any money in a deposit. |
| Credit Line Review | 6 months | Automatic consideration for a higher credit line in as little as 6 months of on-time payments. |
| Foreign Transactions | $0 fee | No foreign transaction fees, which is uncommon on a no-annual-fee starter card. |
| Fraud Protection | $0 liability | You are not responsible for unauthorized charges. |
| Credit Monitoring | Free CreditWise | Monitor your credit score for free with CreditWise from Capital One. |
Pros
- No security deposit required
- No annual fee and no foreign transaction fee
- Automatic credit line review in as little as 6 months
- $0 fraud liability and free CreditWise monitoring
- Open to people with fair or limited credit
Cons
- No rewards program
- High 28.99% variable APR with no intro offer
- May be hard to get approved with poor credit
- Starting credit limit is not guaranteed
The yearly fee charged to keep the card active.
A recurring monthly charge for this card.
Fee charged when transferring balances from another card.
Additional fee for purchases processed in foreign currencies.
Fee charged when withdrawing cash from your credit line.
Penalty fee if your payment is made after the due date.
Standard APR applied to regular purchases.
APR applied to balance transfers.
APR charged on cash advances, usually higher than regular APR.
Higher APR that can apply after late or missed payments.
Promotional APR available for an introductory period.
How long the introductory APR remains in effect.
Requirements
Additional Information
The Capital One Platinum Credit Card is a no-frills, unsecured card for people with fair or limited credit who want to build a history without paying a security deposit. It has no annual fee and no foreign transaction fee, and Capital One may automatically consider you for a higher credit line in as little as 6 months. It includes $0 fraud liability, free CreditWise credit monitoring, and account alerts through Eno, the Capital One assistant. The trade-offs are no rewards and a high 28.99% variable APR with no intro offer, so pay your balance in full each month. If your credit is poor, you may have better approval odds with a secured card such as the Capital One Platinum Secured.
Why we picked it: We chose this card for the lowest deposit among our picks and an automatic credit line review in as little as six months, which can raise your limit without more money down.
5. Capital One Quicksilver Secured
The Capital One Quicksilver Secured Cash Rewards Credit Card earns unlimited 1.5% cash back on every purchase, plus 5% on hotels, vacation rentals, and rental cars booked through Capital One Travel. It requires a refundable deposit of at least $200.
Last updated October 1, 2026
Capital One Cash Rewards
Earn unlimited 1.5% cash back on every purchase, every day, plus 5% cash back on hotels, vacation rentals, and rental cars booked through Capital One Travel. Capital One reports your account activity to the credit bureaus, and you can be considered for a higher credit line in as little as 6 months. You may also work toward earning back your refundable deposit as a statement credit through responsible use.
| Category | Reward Rate | CAP |
|---|---|---|
| Capital One Travel (hotels, vacation rentals, rental cars) |
5%
Booked through Capital One Travel
|
Unlimited |
| All Other Purchases |
1.5%
Unlimited rewards
|
No limit |
| Benefit | Value | Details |
|---|---|---|
| Security Deposit | $200 minimum | Refundable deposit that sets your credit line, starting at $200. |
| Credit Line Review | 6 months | Automatic consideration for a higher credit line in as little as 6 months. |
| Deposit Refund | Refundable | Use your card responsibly and pay on time to work toward earning your deposit back as a statement credit. |
| Foreign Transactions | $0 fee | No foreign transaction fees. |
| Fraud Protection | $0 liability | Zero liability protection against unauthorized charges. |
Pros
- Unlimited 1.5% cash back, rare on a secured card
- 5% back on hotels, vacation rentals, and rental cars via Capital One Travel
- No annual fee, no foreign transaction fee, and no penalty APR
- Automatic credit line review in as little as 6 months
- Refundable deposit
Cons
- $200 minimum security deposit
- High 28.99% variable APR with no intro offer
- Low $200 starting credit limit
- No welcome bonus
The yearly fee charged to keep the card active.
A recurring monthly charge for this card.
Fee charged when transferring balances from another card.
Additional fee for purchases processed in foreign currencies.
Fee charged when withdrawing cash from your credit line.
Penalty fee if your payment is made after the due date.
Standard APR applied to regular purchases.
APR applied to balance transfers.
APR charged on cash advances, usually higher than regular APR.
Higher APR that can apply after late or missed payments.
Promotional APR available for an introductory period.
How long the introductory APR remains in effect.
Requirements
Additional Information
The Capital One Quicksilver Secured Cash Rewards Credit Card is the rewards-earning version of Capital One’s secured card for people with limited or poor credit. You put down a refundable deposit of at least $200, which sets your starting credit line, and you earn unlimited 1.5% cash back on every purchase plus 5% on hotels, vacation rentals, and rental cars booked through Capital One Travel. There is no annual fee and no foreign transaction fee, and Capital One may automatically consider you for a higher credit line in as little as 6 months. The trade-offs are the $200 minimum deposit, which is higher than the $49 entry point on the Capital One Platinum Secured, and a high 28.99% variable APR, so pay your balance in full each month.
Why we picked it: We chose this card for its simple flat-rate rewards, with no categories to track, no annual fee, and a possible credit line review in as little as six months.
How We Chose the Best Beginner Credit Cards
Our editorial team reviewed dozens of starter credit cards from major issuers to identify the best options for beginners. We prioritized cards that are accessible to new credit users and offer strong credit-building potential and long-term value.
We focused on accessibility for beginners rather than on premium rewards, as approval and credit-building are more important when starting out. This method aligns with major financial publishers, who evaluate starter cards based on eligibility, fees, and credit-building features, based on guidance from Consumer Financial Protection Bureau and major credit bureaus.
Primary Factors
We prioritized these factors because they directly affect a beginner’s ability to qualify for a card and build credit.
- Approval difficulty: We focused on cards designed for applicants with no credit, limited credit, fair credit, or student profiles.
- Annual fees: We preferred cards with no or low annual fees to minimize costs for beginners.
- Credit bureau reporting: Only cards that report to all three major credit bureaus (Experian, Equifax, and TransUnion) were considered.
- Upgrade opportunities: We rated cards higher if they offer graduation to unsecured cards, credit limit increases, or product upgrades.
- Security deposit requirements: For secured cards, we evaluated minimum deposits, flexibility, and refund policies.
- Issuer reliability: We preferred established issuers with strong customer support and security standards.
- Interest rates (APR): Although beginners should avoid carrying balances, we ranked cards with excessively high APRs lower.
Secondary Factors
These factors were used to differentiate cards once primary requirements were satisfied:
- Rewards structure: Cashback or straightforward rewards programs were viewed as additional benefits rather than primary considerations.
- Mobile app features: Account management, payment alerts, and spending trackers.
- Credit monitoring tools: Free credit score access and educational resources were considered beneficial.
- Customer experience: Issuer reputation, service quality, and overall user experience were evaluated.
- Fraud protection features: Zero liability coverage and transaction alerts.
- Financial education tools: Cards providing educational resources for beginners received additional consideration.
- Account management flexibility: Autopay options, due date flexibility, and digital statements.
- Foreign transaction fees: Considered for beginners who may travel or make international purchases.
How to Choose the Right First Credit Card
Choosing your first credit card is less about maximizing rewards and more about finding a card you can qualify for and use to build a strong credit foundation. The right beginner credit card should match your financial situation, approval chances, and long-term credit goals. If you’re new to credit, focus on these key decision factors before applying. You can also read our detailed guide on how to choose a credit card  How to Choose the Best Credit Card for Your Spending and Goals in 2026 to understand key features, fees, and eligibility factors before making a decision.

How Beginners Can Build Credit Faster
When used responsibly, your first credit card can help you establish a credit profile within months and improve your credit score within the first year. Since credit scores depend on payment history, credit usage, and account age, beginners can make steady progress by adopting disciplined habits.
Follow these proven strategies to build credit faster and avoid common beginner mistakes:
Who Should Apply for a Beginner Credit Card?
Beginner credit cards are intended for individuals new to credit or with limited credit history. These cards generally offer easier approval and help users build a solid financial foundation.
- First-time credit users: If you have never used credit before, a beginner credit card can help you establish your credit profile. Responsible use, including timely payments and low balances, can generate your first credit score within a few months. This is often the first step toward qualifying for more favorable financial products.
- Students: Students often have limited income and no credit history, making beginner or student credit cards a practical starting point. These cards typically feature easier approval and may offer educational resources. Building credit early helps students establish a strong credit history before entering the workforce.
- Young professionals: If you have recently started your first job, a beginner credit card can help you build financial credibility. With a steady income, you may also qualify for entry-level unsecured cards. Establishing credit early supports future loan, housing, and premium credit card approvals.
- Immigrants building U.S. credit: New immigrants often need to build credit from the beginning, as foreign credit history typically does not transfer to the U.S. system. Beginner credit cards, particularly secured cards, can help establish a new credit profile. This is important for renting housing, financing purchases, or qualifying for better financial products.
- Anyone with a thin credit history: Even with existing credit accounts, you may have a “thin credit file” if your history is limited. Beginner cards can strengthen your profile by adding positive payment history. Over time, this can improve your credit score and expand your financial opportunities.