Alex Lost 28 Points in One Month
Alex had never missed a payment on his credit cards and had even paid off balances early. So when he was approved for a new card with an interest rate significantly higher than he was expecting, he was confused about what went wrong.
After further review, he understood the problem was not the timing of payment, but rather the balance reflected at the end of the statement cycle. For this month, the statement balance was unusually high, increasing credit utilization, which led to a 28-point score reduction. This is a point to consider: to have a good credit score, it is not just important to pay on time, but also to monitor credit use.
Alex consistently paid his credit card bills on time, often early. Despite this, his credit score dropped by 28 points in one month. The decrease was not due to a late payment, but rather how closing a credit card statement  credit card statement impacted his score.
This example highlights that many people are unaware that their credit score is affected by more than timely payments. Your credit score continues to influence lending decisions, even if you pay your bills on time.
What is a credit score?
A credit score is a three-digit number that indicates a consumer’s likelihood of repaying borrowed money on time. According to the Consumer Financial Protection Bureau (CFPB) , the credit score scale ranges from 300 to 850, with higher scores indicating lower credit risk.
In other words, the definition of credit score can be narrowed to a trust factor. The banks and credit card companies rely on your credit score to make a yes or no decision on lending you money, based on which they will charge you an interest rate.
One of the most widely used credit models is the FICO credit score, which nearly all lenders in America currently use for credit card, personal loan, and mortgage lending.
How is a credit score calculated?
The credit score calculation used by FICO follows a consistent formula. While the exact math isn’t public, the credit score percentage breakdown is well known.
Credit score factors (FICO Model)
| Factor | Weight | Impact Level |
|---|---|---|
| Payment history credit score | 35% | Very High |
| Credit utilization ratio | 30% | Very High |
| Credit history length | 15% | Medium |
| Credit mix meaning | 10% | Low |
| New credit inquiries | 10% | Low |
Together, these credit score components form the foundation of your score.
This is the most important factor and answers a straightforward question: Do you pay on time?
-
- Late payments may remain on your credit report for seven years.
- According to Equifax
, even a single 30-day overdue payment can significantly lower your credit score.
- Paying at least the minimum by the due date protects your credit score.
- Late payments may remain on your credit report for seven years.
Consistency is more important than perfection when it comes to credit cards.
Your credit utilization ratio measures the percentage of available credit you’re using.
Example: $2,000 balance on a $10,000 limit = 20% utilization
What many beginners miss:
-
- Utilization is calculated when your statement closes, not when you pay.
- Even with low overall usage, high utilization of a single card can hurt badly.
One of the quickest ways to increase a credit score is by keeping utilization below 30 percent, ideally below 10 percent.
The length of your credit history makes up about 15% of your total FICO score. It shows how long you have been using credit.
The average age of all your credit accounts shows how consistent your credit use has been. When you open a new credit card, your average account age goes down for a while, no matter how well you pay your bills. Closing older cards can lower your average account age even more, especially after those closed accounts drop off your credit report. While no-fee credit cards can help you have a mix of credit types, you should think about how opening or closing accounts might affect your average account age.
Credit mix is approximately 10% of your overall FICO score and refers to the types of credit that you manage. These can include credit cards, auto loans, and mortgages. A credit mix can be favourable if you manage various kinds of credit. A high percentage of bad credit can significantly impact your credit score.
However, you don’t need each type of credit to have a healthy credit score. Many consumers can attain top-notch credit scores by using only credit cards, especially at a younger age when you are initially starting your credit experience. The type of credit you have becomes relevant later, once you are established with a strong payment history and using your credit accordingly.
A better strategy for both beginners and experienced borrowers is to use credit cards responsibly instead of taking on new credit to improve their credit mix.
Inquiries for new credits also constitute about 10% of your credit score. Whenever you apply for a credit card or a loan, your lender performs a hard inquiry on your credit report.
Key points to know:
-
- Just one query can reduce your score by a few points.
- Several applications within a brief time frame can imply a higher risk for the lender.
- Equifax
It’s especially important to space out applications when establishing credit for the first time. It will help to protect your score and increase your chances of being approved for other credit cards in the future.
Credit score ranges explained
Credit score ranges help you understand what your score means and how lenders may view your application. Most credit scores fall between 300 and 850, with each range reflecting a different level of risk to the lender. When you know where your score stands, you gain an advantage because a higher score usually leads to better approval chances, lower interest rates, and higher credit limits.
| Credit Score Range | What It Means |
|---|---|
| 300–579 | Poor |
| 580–669 | Fair |
| 670–739 | Good |
| 740–799 | Very Good |
| 800–850 | Excellent |
If you’re wondering what a good credit score is, most lenders consider 670 or higher to be good credit.
A high credit score typically means lower APRs, higher credit limits, and greater flexibility when applying for loans or buying a home.
How credit cards help you build credit
Credit cards are among the most effective ways to build credit because they report their activity to credit bureaus monthly. Compared to taking out a loan, using a credit card will give you multiple months to show responsible behavior, which will affect your credit score.
Credit scores can be built by focusing on the following basics:
- Pay on time, every time: Making payments on time can improve your payment history, which is the most significant factor that determines your credit scores.
- Keep balances low: Keeping balances low reflects positively on your ability to manage credit responsibly without overusing it.
- Use cards frequently, but lightly: By charging small amounts regularly. This will keep accounts active and establish a positive credit history.
These habits are effective whether you are new to credit, building your credit, or rebuilding it. Properly managed credit cards establish a positive credit history, which also improves your credit score.
Finsery Pro Tip
How long does it take to build credit?
If you are wondering how long it takes to establish credit scores, the key factor is consistency, not speed. Credit scores reflect patterns of behavior over time, and lenders value predictability and steady financial habits.
Generally, people perceive progress in levels:
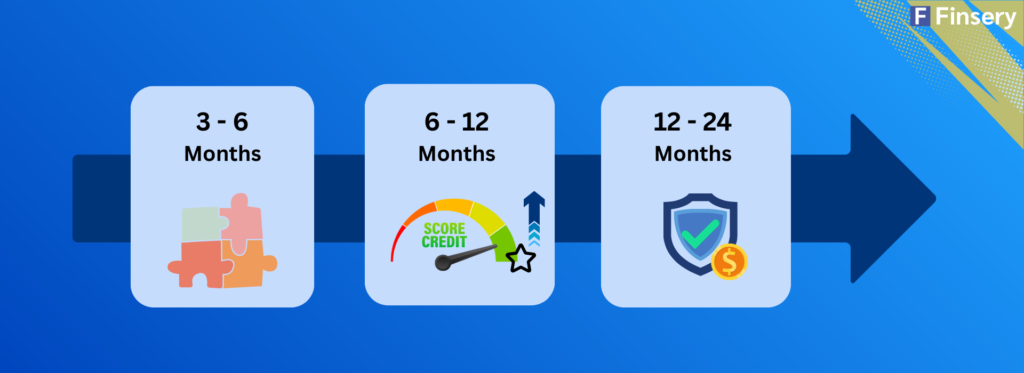
- 3-6 months: The process of acquiring a credit score will begin when your first credit card or loan is reported to a credit bureau. In this level, a single payment can help, though you might see your credit scores increase a bit.
- 6–12 months: By making on-time payments and maintaining a low credit utilization rate, you will see improvements. This is the point at which many people work to improve their credit scores to be eligible for better entry-level credit cards.
- 12–24 months: Your credit record will become more stable as the average age of your accounts increases and your usage patterns are established. Creditors will then view you as a less risky borrower.
At this stage in your credit journey, you may qualify for lower-APR credit cards, higher credit limits, and better rewards programs. While there is no quick fix, credit scores can improve more quickly than expected with the right habits. Consistent use of credit cards and responsible payments are essential for long-term success. Building credit takes time, so remain patient and consistent. Steady progress is more effective than rushing.
Credit scores aren’t built by shortcuts — they’re built by consistent habits that get reported month after month.
How to improve your credit score
If you want to know how to improve your credit score in a hurry, you need to begin by implementing strategies that impact the most significant credit-score-weighting factors. Although you can’t do it overnight, consumers who use credit cards can implement changes that create a positive impact within a few statement cycles.
The three best approaches are:
- Paying down credit card balances to lower your credit utilization ratio has a significant impact on your credit score
- Avoiding new credit inquiries unless necessary, since multiple applications in a short time can slow score growth
- Keeping older accounts open to protect your credit history length and maintain stability
Paying in full reduces usage and prevents interest from accruing. Rapid credit score increases can be achieved through clever, low-risk behavior.
Credit Building is a Pattern, Not a Shortcut
- Having good credit isn’t about shortcuts; it’s about making habits. Paying your bills on time and keeping small balances on your credit cards are key to improving your credit scores.
- That was the point that Alex was taught. He came to understand that it was not the time he paid the bill but rather the balance reflecting when the statement closed. The solution was to pay before the statement date, and thus Alex’s score steadied.
Frequently Asked Questions
Back to topEven if you paid on time, your score can drop if your reported balance increases. Credit card issuers usually report your balance around the statement closing date, so if the statement closes with a higher balance, your credit utilization ratio rises, and your score may temporarily decrease.
Yes, paying early helps lower the balance before it gets reported, which reduces your credit utilization. Lower utilization generally supports a better score, especially if you bring your balance down before the statement closing date.
To avoid fees and interest, the due date is the most crucial consideration. However, for improving your credit score, the statement closing date matters more because your utilization is primarily based on the balance reported at statement closing, not what you pay later
Your current balance changes daily as you spend and pay. Your statement balance is the amount recorded on the statement closing date. Since issuers typically report monthly statement information, the statement balance often has the most significant impact on your reported credit utilization.
No, checking your own credit score is a soft inquiry that does not lower your score. Only hard inquiries, such as applying for a credit card or loan, can slightly affect your score.
Most credit card companies report to the credit bureaus once per month (at the end of the billing cycle). This is why the balance shown on your statement is often the one reported. The Consumer Financial Protection Bureau (CFPB) explains that credit card periodic statements include the billing cycle closing date and the balance information for that cycle.
Not necessarily, but it isn’t always ideal. If your cards consistently report a $0 balance, scoring models may not see active credit usage. Many consumers achieve better results when a single card reports a small balance, usually around 1%–9% utilization. According to Experian , having an active credit card account with low utilization can be better for your FICO Scores than having no utilization at all.
