At Finsery, we provide independent, research-driven financial content. To keep our articles, tools, and resources free for readers, we may receive compensation from companies featured on our site through affiliate links, referral partnerships, or paid placements. This compensation may influence how and where products appear on our site (such as the order or placement of products within categories), but it does not affect our editorial opinions, recommendations, or reviews, which remain based on objective analysis. While we strive to ensure the accuracy and timeliness of all information, Finsery makes no representations or warranties regarding the completeness, applicability, or future availability of any product, service, or offer. Product terms, conditions, and policies are provided by the respective companies and may change without notice. We do not include every company or financial product available in the marketplace. Some offers may be subject to eligibility requirements, approval processes, or geographic restrictions. Your personal circumstances may impact whether a product is right for you. Any compensation received by Finsery does not constitute an endorsement of any company or product. All content is provided for informational purposes only and should not be considered personalised financial, investment, tax, or legal advice. Please consult a certified professional for advice specific to your situation.
What is Credit Utilization? How it Affects Your Credit Score
Editorial Note: The information provided on Finsery is for general informational purposes only and is not intended as financial or professional advice. Our team conducts independent research to share insights we believe are accurate and helpful at the time of publication. Some of the products or services featured on this page are from our advertising partners, who may compensate us if you click through links on our site. However, affiliate relationships do not influence our editorial opinions, our reviews and recommendations remain based on our own independent research and analysis.
Editorial Note: Finsery provides general informational content only, not financial advice. We may earn a commission from our advertising partners when you click links, but our editorial opinions remain independent.
Credit utilization is the percentage of your available revolving credit that you’re using. It is calculated by dividing your reported balance by your total credit limit and multiplying by 100. Lower utilization is generally better for your credit scores, and people with the highest scores often have utilization below 10%. However, there is no universal percentage that guarantees a specific score.
How Credit Utilization is Calculated
Credit utilization is calculated by dividing your reported revolving balance by your total revolving credit limits, then multiplying by 100. If you have multiple cards, you can calculate utilization for each card separately or across all cards combined.
Per-card utilization is the percentage of one card’s balance compared with that card’s own limit. Overall utilization is the percentage calculated across your qualifying revolving balances and limits combined. Use the calculator below to see how both measures apply to your cards.
 Finsery Credit Utilization Tool
How your credit utilization is calculated
Compare individual card utilization with your overall utilization.
Card 1
Card 2
Overall utilization
- Total limit
- —
- Total balance
- —
Overall utilization not calculated yet.
Enter a valid credit limit and balance for both cards to see your overall utilization.
Want to check with multiple cards? Use Finsery’s credit utilization calculator  Credit Utilization Calculator to calculate your multiple per-card and overall utilization.
Credit Utilization: What Different Utilization Levels Look Like in Dollars
Here’s how much your balance would be at 10% and 30% utilization for different credit limits.
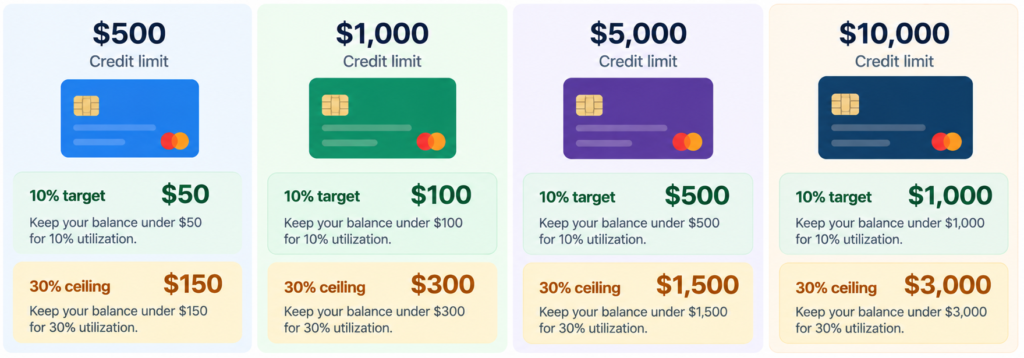
These amounts simply apply the utilization formula to each credit limit. A 30% utilization rate is a common benchmark, not a hard scoring cutoff. FICO says there is no single optimal percentage, and lower utilization is generally better.
What is a Good Credit Utilization Ratio?
A good credit utilization ratio is generally a low one. Under 30% is a practical benchmark, while single-digit utilization is often associated with the strongest FICO Score profiles. There is no universal percentage at which utilization suddenly changes from “good” to “bad.”
Here’s how different utilization levels compare:
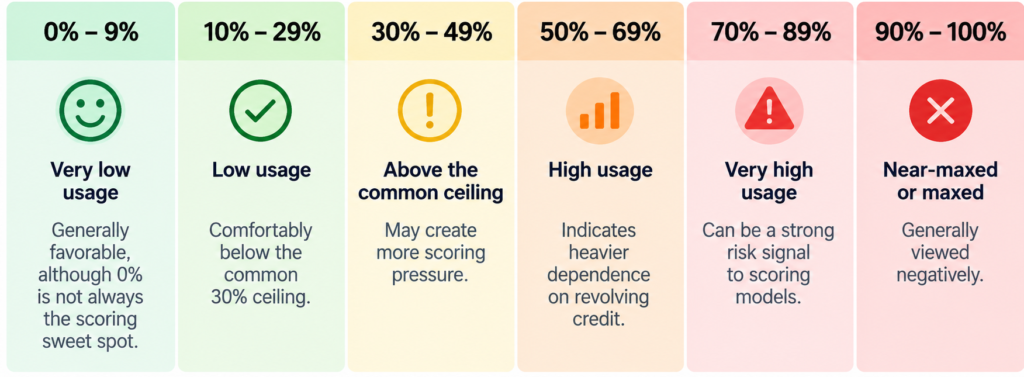
The key point is that these bands describe direction and risk, not guaranteed score changes. A person moving from 70% to 40% may see a different result from someone moving from 20% to 8%, because scoring depends on the complete credit profile and the model being used.
Experian reported 28.3% average credit card utilization in March 2026, with utilization much lower among consumers with higher FICO Scores. Average utilization was 6.4% for Exceptional, 14.6% for Very Good, 38.5% for Good, 59.2% for Fair and 76.8% for Poor. These figures are based on Experian data from March 2026 .
Is 30% bad? What about 50%, 70% or 100%?
Thirty percent is not a magic cutoff that automatically damages a score. It is better treated as a ceiling because utilization generally becomes less favorable as the percentage rises. FICO itself says the data does not support a single optimal 30% threshold.
At 50%, you are using half of the available revolving credit being measured. That is high enough to deserve attention, particularly if one card is close to its limit.
At 70%, utilization is very high and can be a significant negative factor. At 90% or 100%, a card is nearly maxed out or maxed out, which can signal a much heavier reliance on available credit.
Why High Utilization Lowers Your Credit Score
High utilization can lower your credit score because scoring models view high revolving balances relative to your limits as a sign that you may be relying heavily on available credit. This mainly applies to revolving credit, especially credit cards. FICO also considers personal lines of credit, while HELOCs are generally excluded from its utilization calculation.
The three major credit bureaus, Equifax, Experian and TransUnion, maintain your credit reports, and scoring models use the information reported there rather than monitoring your card activity in real time. For FICO Scores, amounts owed account for about 30% of the score, with utilization playing a major role within that category. Payment history is the largest factor at 35%.
VantageScore weights utilization differently. Its published VantageScore 4.0 framework assigns credit utilization a 20% weight, while other VantageScore explanations have put it at roughly 20% to 30%, depending on the model and source. The takeaway is simple: utilization is an important scoring factor, but its exact impact varies by scoring model.
Why does high utilization lower your score?
The underlying logic is risk. A person using a large share of a revolving credit line has less unused borrowing capacity and may look more financially stretched than someone using a small share.
What this does not mean: A low ratio does not replace on-time payments. Utilization also does not usually create a permanent penalty in the way a serious negative payment-history event can. When a newer reported balance falls, many scoring models can respond to that newer information.
What Credit Utilization Do Lenders Prefer on an Application?
There is no universal utilization percentage that every lender requires or prefers for approval. Lower revolving utilization can strengthen an application, but lenders also consider your credit score, credit history, income, existing debt and debt-to-income ratio. If you are preparing to apply for a major loan or a new card, reducing a high reported balance before the lender pulls your credit can help. The benefit depends on when your card issuer reports the updated balance to the credit bureaus.
A lender may still approve someone with 40%, 50% or higher utilization if the overall application is strong. Approval is an underwriting decision, not a utilization-score lookup. An issuer can also make its own decision based on criteria that are not part of your credit score. For example, income is not included in your credit score, but lenders may use it to assess your ability to repay and calculate your debt-to-income ratio.
Finsery view: Treat 30% as a benchmark, not a target. Lower utilization gives you more room for scoring-model differences, reporting timing and unexpected purchases.
Does Credit Utilization Matter If You Pay in Full?
Yes. Credit utilization can matter even when you pay your credit card in full every month because the reported balance, not necessarily your live balance, is what scoring models receive from the issuer.
A statement balance is the amount shown as owed when a billing cycle closes. A current balance is what your account shows you owe at a particular moment. A reported balance is the balance your card issuer sends to a credit bureau for that reporting update. A statement closing date is the date a billing cycle ends and the issuer generates the statement balance.
Many issuers report around the statement closing date, but schedules vary. Experian says issuers generally report around statement closing dates rather than the payment due date.
For the timing of the billing cycle itself, see our guide to what a credit card billing cycle is  What is a billing cycle and How does it work? A Complete Beginner’s Guide. Your credit card grace period
 What is a Grace Period on a Credit Card and How Does It Help You Save Money? is a separate concept from utilization: it concerns when you can generally avoid purchase interest by paying the statement balance on time.
How to Lower Credit Utilization
The fastest way to lower your reported ratio is usually to reduce the balance before the issuer reports it. Other strategies can help, but they can introduce costs, risks or timing uncertainty.
1. Pay before the statement closing date
This is usually the simplest and fastest lever when you have cash available.
Finsery view: For most people, the fastest and cheapest lever is paying before the statement closing date, not opening another card. You can reduce the reported percentage without taking on another account.
2. Pay twice a month
Two payments can help keep the balance lower throughout the billing cycle and make large purchases easier to manage.
Finsery view: Paying twice a month can help keep your reported balance lower, but only if the payments post before your issuer reports the balance.
3. Request a credit limit increase
A higher limit can reduce the ratio even when the dollar balance stays unchanged.
Finsery view: A higher limit can lower utilization without reducing your balance, but only request one if you can avoid taking on more debt.
4. Keep existing no-fee cards open
Finsery view: Keeping a no-fee card open is usually smarter than closing it, unless it tempts you to overspend. The goal is useful available credit, not a larger wallet for its own sake.
5. Lower balances with larger one-time payments
Using a windfall, tax refund or other available cash to reduce card balances can bring utilization down quickly.
Finsery view: For a longer-term plan, focus on how you use cards rather than chasing a percentage every month. Our guide to using credit cards without going into debt  How to Use Credit Cards Without Going Into Debt: A Step-by-Step Guide covers that broader habit.
6. Update your income with the issuer
An updated income figure can sometimes support a higher credit limit, which can indirectly lower utilization.
Finsery view: Updating your income can support a higher credit limit, but it’s not a guaranteed way to lower utilization. Keep the information accurate and only report income you can reasonably support.
How Fast Does Your Score Recover After You Lower It?
A lower utilization ratio may help your score after the new balance reaches the credit report and the scoring model evaluates that updated information. There is no universal number of days or points because reporting schedules, scoring models and credit profiles differ.
In models that primarily use the latest reported balance, a lower balance can matter as soon as the new information is reported and the score is recalculated. TransUnion says there is no standard day for credit reports to update because TransUnion says lenders generally report around monthly but not on the same day.
Trended data is credit information collected over time that lets a scoring model evaluate patterns rather than only one snapshot. FICO Score 10T, for example, considers a historical view of balances and limits over roughly the previous 24 months or longer.
VantageScore 4.0 also incorporates trended credit data, giving the model a longer view of borrowing and payment patterns. VantageScore describes this as a way to see changes in behavior over time rather than relying only on static point-in-time information.
That means a one-month improvement can matter quickly in some models, while models that use historical trends may interpret the same improvement in the context of your longer pattern.
How much will lowering utilization change your score?
It can move your score in a favorable direction, but nobody can responsibly promise a specific point increase from utilization alone. The effect depends on the scoring model, your starting utilization, the rest of your credit profile and what other information changed at the same time.
Credit Utilization Myths
Myth: You need to carry a balance to build credit
Fact: You do not need to pay interest or carry debt from month to month to demonstrate responsible card use. A small reported balance can be useful in some scoring models, but that is different from carrying debt and paying interest
Myth: 30% is the exact cutoff
Fact: Thirty percent is a common benchmark, not a universal scoring cliff. FICO says there is no single optimal utilization percentage and that lower is generally better.
Myth: 0% utilization is always best
Fact: Not necessarily. FICO says having no revolving balance reported can be slightly less favorable than having a small reported balance, all else equal. That is why 1% to 9% is generally treated as a better target than deliberately forcing every card to report 0% every month. You do not need to carry interest-bearing debt to achieve that activity.
Myth: A high utilization ratio stays on your report for years
Fact: Utilization is generally a snapshot or, in some newer models, part of a trend. A high reported balance can hurt while it is being used by a scoring model, but lowering the balance can change the picture. FICO Score 10T is the key example of a model that considers longer-term trends.
Myth: Closing an old card always improves your credit
Fact: Closing an empty card can remove available credit and increase your overall utilization. The effect depends on your remaining balances, limits and credit profile.
Frequently Asked Questions
Back to topThirty percent of a $5,000 credit limit is $1,500. You calculate it by multiplying $5,000 by 0.30. A $1,500 reported balance therefore represents 30% utilization on that card. Thirty percent is a common ceiling, not a guaranteed threshold for how a scoring model will treat your account.
Using 90% or 100% of a revolving credit limit creates very high utilization. That can negatively affect your credit score because a scoring model may interpret heavy use as greater repayment risk. A maxed-out card can also matter even when your overall utilization is lower because per-card utilization may be considered.
Paying twice a month can lower your reported utilization when the payments reduce the balance before your card issuer reports it. For example, paying $1,000 off a $1,200 balance before the reporting date leaves $200 to be reported. The number of payments itself does not improve the ratio; the lower reported balance does.
A $1,500 limit is not harmful by itself. The problem is that a low limit makes utilization rise quickly with ordinary spending. A $300 balance on a $1,500 limit is 20%, while the same $300 balance on a $5,000 limit is only 6%. Your limit also does not determine whether an issuer will approve future credit.
For a 10% target, $50 on a $500 limit equals 10%. For the common 30% ceiling, $150 equals 30%. These are utilization targets, not amounts you need to carry as debt. You can spend more during the billing cycle and make payments before the relevant reporting date to keep the reported balance lower.
No. A $70,000 salary does not translate to a fixed credit limit because issuers set credit lines individually. They can consider income, existing debts, credit history, scores, application information and their own underwriting policies. Income itself is not part of standard credit-score calculations, but lenders can use it when evaluating whether you can afford additional payments.
At 26.99% APR, a $3,000 balance carried for roughly one month would generate about $67 using the simple calculation $3,000 × 0.2699 ÷ 12 = $67.48. This is approximate and ignores daily compounding, the exact billing cycle and transaction timing. See our guide to credit card interest  What is a Credit Card Interest and How Does It Work? A Simple Guide for how card interest actually works.
For a typical FICO Score, payment history is the largest category at 35%, followed by Amounts Owed at 30%, which includes utilization. That means paying on time should remain your first priority. Lowering utilization can help, but it does not compensate for a history of missed payments.
Closing a credit card can hurt your score when it reduces your available revolving credit and pushes your overall utilization higher. The effect depends on your balances, limits and complete credit profile. An account’s age and other factors may also matter. If the card has no fee and is not encouraging overspending, keeping it open can be the better choice.
High utilization can affect your score, while the high balance is reflected in the data used by the scoring model. Once lower balances are reported, newer-balance models may respond to that change. Models using trended data, such as FICO Score 10T and VantageScore 4.0, can also consider longer-term utilization patterns, so the effect is not identical across models.
The content on Finsery is created for informational and educational purposes only and should not be taken as financial advice. While we do our best to ensure accuracy and relevance at the time of publication, details may change over time or vary by individual circumstance. Finsery may earn a small commission when you click on certain links, but our editorial opinions remain independent. See our full disclaimer.
Editorial Note: Finsery content is informational only, not financial advice. We may earn from links; our opinions stay independent. See our full disclaimer.


